Why invest in stocks?
You buy in stocks - because you get to own companies.
Ownership. This is more exciting than earning a profit on trades or flips. You actually have a stake in something that is so important, that hires some people and pays taxes to the Government for its programs.
The stock market platform is a platform where you can buy and sell ownership of companies fairly and equally. They can attract investors to trade fairly. They help companies to raise funds from us in a highly liquid market, where shares can be easily traded.
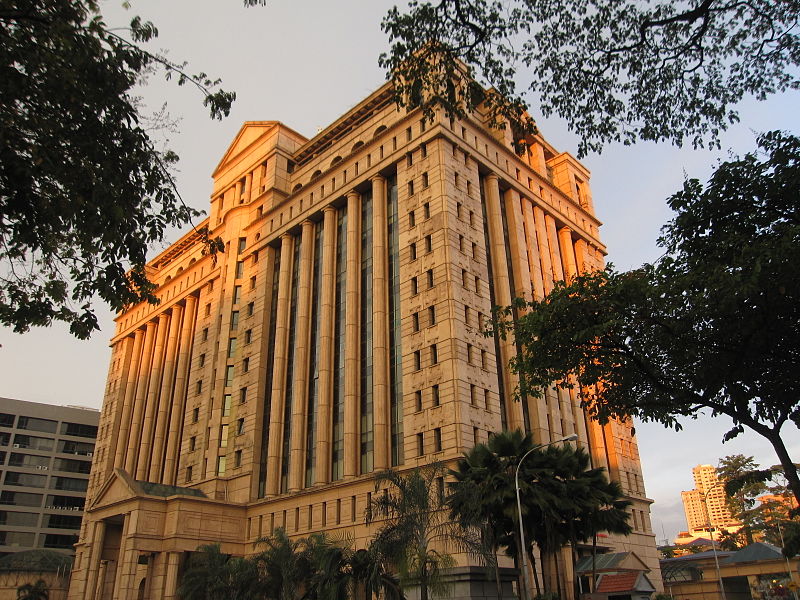 |
| Kuala Lumpur Stock Exchange |
When a stock is listed, it must meet certain criteria. A company's stock on the catalist needs to be sponsored by a financial institution. To list on the mainboard, a company needs to meet certain criteria of scale, such as pre-tax profits of S$30 million in more than three financial years recently, and capitalisation of more than S$150 million.
There are different stocks to buy. They include: stocks, real estate investment trusts (REITs, where property and financial institutions' managers bundle properties into tradable portions), exchange traded funds (ETFs), warrants, extended settlements, bonds and preference shares.
For REITs listed in Singapore, there are 34 of them in 6 different categories: residential, office, retail, hotel, industrial and hospitality. Although interest rate environments are difficult for REITs, I think given the recent property cooling measures, it is actually more attractive to invest in residential REITs that cater to the
higher end markets than in mass-market or suburban developments.
ETFs, on the other hand, buys and sells shares to reflect performance without the use of a fund manager, in accordance to an indicator. Examples include Lyxor, SPDR, STI ETF by Nikko AM, and so on.
Bonds are fixed IOUs where we buy a company's borrowings. Unfortunately, liquidity in Singaporean bond markets is not liquid enough, as we are a small market.
Preference shares are shares that give us a higher priority than ordinary shareholders, when companies dissolve and distribute residual profits. In exchange for a fixed dividend, preference shareholders do not hold voting shares. Also, there might not be maturity dates on preference shares, unless they are callable hares.
There are two schools of thought in share investing: technical analysis (TA) and fundamental analysis (FA).
TA is the art of predicting the future price movements of a company, based on both price and volume. TA gives us a point of reference on when we can enter and exit a market. Most stock beginners tend to be carried away by the hoopla of TA, because they will remember the patterns and candlesticks of intraday and inter-day charts, and make a living out of timing the markets. But the market is not made up of just winners. People are as likely to lose money as they do gain profits in the stock market. Indeed, only 5% of traders consistently succeed. I am trying my best to be one of the top 5%.
One should buy companies at the right pricing and exit at the right juncture. Hence, TA is useful as a guide to stock entry. However, it shouldn't be used alone.
Enter FA.
For new investors, I would strongly recommend they learn FA, if they want to get serious about share investing. If you need some guidance on share picking, do +1 or contact me on Google+ or Blogger. It will take some time as I have a day job (explaining the long gap between posts on this blog), but FA will definitely be worth it. The good thing is, to trade stocks, you just need to be old enough to legally trade them, and you have the desire to know more about the companies you are investing in.
Stock market investing should be a pleasant, sweet experience. We should preferably invest in the companies that we understand well. We should be familiar with the business models of the firms, understand that they are in great financial health, being satisfied with their returns and capital gains and satisfied at their growth or corporate development.
The main tool FA aficionados use is the Price-Earnings, or P/E ratio. Earnings grow, but the prices may not reflect the growth of earnings proportionately.
For stocks with a P/E ratio of below 10, they are deemed as 'cheaper'. For stocks with a P/E ratio of above 20, they are deemed as expensive. Most firms have P/E ratio of between 10 and 20. This means, when a firm has a P/E ratio of 5 to 9 and it is doing well, we should snap it at the right timing from TA trends. When a firm has unsustainable P/E ratio of more than 25 times, unless it is a growth stock with exciting developments the firm can afford to pay, I would not touch the stock.
When you invest in shares, you have to take note of cumulative dividends and cumulative rights, or cum dividend/CD or cum rights/CR in short. Stocks with CD do not yet distribute dividends, while stocks with XD (eX-dividend) has already distributed dividends. For CR, they are meant to help the company to raise money for existing shareholders. The company is issuing more shares, and it may offer current shareholders to buy new shares at discounted prices.
Earlier, I mentioned that buying shares mean buying shares of management in the company. You do not hold physical certificates in owning shares these days. They are kept with the Central Depository. Unless you go to their office to ask for share certificates, you don't get share certificates to show you're an owner of some shares of the company.
When you look at stocks, you have to consider the operations of a firm.
Basic ratios have to be profitability ratios (
gross and
net profit margins), liquidity ratios (think
current ratio) and
solvency ratios (along with
interest coverage ratio). It has to be one with solid potential growth in the next 5-10 years. With globalisation, I expect the typical telecommunications, logistics, transport and hospitality-linked firms to keep growing. Also, with climate change, oil prices may not sink forever, and this may result in the rise of commodities, alternative energy (think oil palm, for example) and water.
You can trade your stocks either through a remisier/trading representative, or through the online platform of your stock broker. The trading representative is still relevant to you because he may manage your transactions and credit risk, as you are supposed to make payments within 3 days of the share transaction.
Brokerage houses charge commission rates. Hence, if you want to minimise your brokerage fees, you try to trade within $8,500 for most companies, as most brokerage houses charge 0.28% fees with a $25 minimum commission rate. If you are going to pay $25 per trade anyway, why not trade at around S$8,000 if you can afford it?
You buy 50% of your stocks at the first opportunity. When you're right, buy 30% more stocks at the second entry point, and 20% at the third one. If you're wrong, sell fast.